If you’re involved in the bulk commodity supply chain, you’ve likely encountered the growing conversation around Scope 3 Emission Reporting. These emissions represent the indirect greenhouse gas (GHG) emissions generated across your entire value chain, from raw material sourcing to product disposal. Unlike Scope 1 and Scope 2 emissions, which stem from a company’s direct operations and energy use, Scope 3 emissions encompass activities outside your immediate control, such as supplier manufacturing, transportation, customer usage, and end-of-life treatment of products.
At first glance, tackling Scope 3 emissions may seem overwhelming. After all, they often account for the lion’s share of a company’s carbon footprint—up to 75% on average. Yet addressing these emissions is not just a regulatory necessity; it’s a strategic imperative for businesses aiming to thrive in a sustainability-driven economy. For innovative companies in the bulk Commodity supply chain, reducing Scope 3 emissions offers opportunities to enhance supply chain resilience, unlock cost savings, and attract eco-conscious customers and investors.
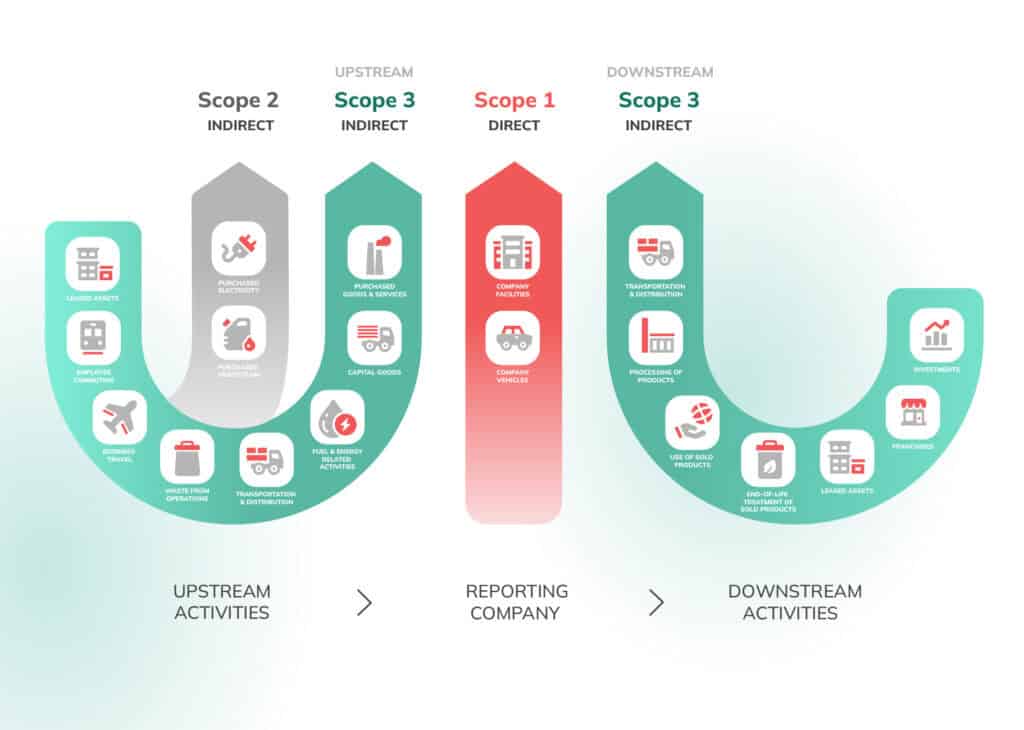
Understanding Scope 3 Emissions
So, what exactly counts as Scope 3 emissions?
The GHG Protocol provides a valuable framework. It’s a widely recognised standard for accounting for business GHG emissions. This method categorises Scope 3 emissions into upstream and downstream sources, along with 15 subcategories under these two categories.
For example:
- Upstream: Emissions from raw material extraction, supplier manufacturing processes, and transportation.
- Downstream: Emissions from customer usage of sold products and waste treatment at end-of-life.
Upstream Emissions
Upstream emissions result from the production of materials and the operation of factories before the creation of final goods. These emissions occur upstream in your supply chain.
Here are all the categories associated with upstream emissions:
- Purchased Goods and Services: These refer to the emissions generated during the production of the materials your company purchases. This includes raw materials and any pre-processing done by suppliers.
- Capital Goods: This category encompasses emissions from manufacturing major items. Examples include buildings, machinery, and even computer software.
- Fuel and Energy-Related Activities: This includes emissions from fuel extraction, production, and transportation. Think fossil fuels, like those used for vehicles and heating buildings, encompassing all emissions produced.
- Upstream Transportation and Distribution: Transporting your goods from suppliers to your facilities.
- Waste Generated in Operations: Emissions from your waste disposal are also calculated.
- Business Travel: These emissions are included if your employees fly or drive for work purposes. This also covers emissions from employee travel for conferences or meetings.
- Employee Commuting: The environmental impact of your employees’ travelling to and from work is also considered. This can involve emissions from personal vehicles or public transportation.
- Upstream Leased Assets: This category encompasses assets leased for operational purposes, including equipment and vehicles.
Downstream Emissions
Downstream emissions refer to those that occur after your product leaves your direct control. These downstream activities are a key part of the overall emissions picture.
Here are all the categories associated with downstream emissions:
- Downstream Transportation and Distribution: This category accounts for emissions associated with delivering finished products to customers.
- Processing of Sold Products: Consider how a business customer might further process your product. For instance, a food manufacturer might refine what you provide to make bread.
- Use of Sold Products: Consider the emissions generated when end users use your products. A product’s overall environmental impact can depend heavily on consumer actions and emission hotspots.
- End-of-Life Treatment of Sold Products: After consumers finish using your products, their disposal method needs to be considered, including recycling or landfilling.
- Downstream Leased Assets: Businesses must also account for rented properties and equipment.
- Franchises: If your brand expands through franchises, the associated emissions are relevant to reporting.
- Investments: Where you invest your money has implications. Your stakes in projects or companies also carry emissions reporting requirements.
Scope 3 Emissions Across Industries
Here’s a breakdown of how different industries compare in terms of their Scope 3 emissions:
| Industry | Key Scope 3 Emission Sources | Emissions Impact |
| Oil and Gas | Use of sold products (fuel combustion), upstream fuel extraction, transportation, disposal. | Very High: Dominates total emissions, often 90%+ of the sector's footprint. |
| Utilities (Electricity) | Combustion of sold electricity (coal, gas), upstream fuel extraction and transportation. | High: Life cycle emissions from fossil fuel-based generation dominate. |
| Mining and Minerals | Downstream use of products (e.g., coal burning, steel production), transportation of raw materials. | Very High: Often 100x Scope 1 & 2 emissions. |
| Steel and Metal Manufacturing | Upstream raw material production (e.g., iron ore), downstream product use (e.g., construction, automotive). | High: Traditional methods emit ~2.33 tons CO2/ton steel; circular methods reduce this. |
| Chemical Manufacturing | Raw material procurement, downstream product use (e.g., fertilizers, plastics), transportation. | Very High: Scope 3 accounts for the majority of emissions in this sector. |
| Agriculture and Food Production | Fertilizers, livestock methane, food processing, packaging, distribution, and cooking. | High: Significant upstream and downstream contributions. |
| Transportation and Logistics | Upstream fuel production, emissions from vehicles operated by third parties, infrastructure development. | Moderate to High: Depends on fuel type and logistics efficiency. |
| Automotive Manufacturing | Raw material extraction (metals/plastics), parts manufacturing, vehicle use phase (fuel combustion), recycling/disposal. | Very High: Vehicle use phase dominates emissions profile. |
| Construction and Real Estate | Emissions from construction materials (cement, steel), building operations, demolition. | High: Buildings account for ~90% of Scope 3 emissions in this sector. |
| Textiles and Apparel | Raw material production (cotton/synthetics), dyeing/finishing processes, garment manufacturing, distribution. | High: Fast fashion supply chains drive significant emissions across all stages. |
Why Measure Scope 3 Emissions?
Scope 3 emissions are more than an environmental challenge—they’re a business risk. Companies that fail to address these emissions face reputational damage, regulatory penalties, and supply chain disruptions. For instance, stringent climate regulations are emerging globally, requiring businesses to disclose and reduce GHG emissions across all scopes.
In Australia, directors face significant penalties for non-compliance with mandatory climate-related reporting requirements, including those related to Scope 3 emissions. These penalties are part of the broader sustainability reporting regime under the Corporations Act 2001 and include civil and criminal consequences.
So, ignoring Scope 3 emissions reporting is not a good idea!
Conversely, proactive management of Scope 3 emissions can deliver significant benefits. You can streamline operations and reduce costs by identifying emissions benefits. Hotspots in your supply chain include energy-intensive suppliers or inefficient transportation routes. Moreover, showcasing a commitment to sustainability strengthens brand reputation and builds stakeholder trust. Customers increasingly prefer businesses that align with their values, while investors reward companies with credible plans for reducing their carbon footprint.

Scope 3 Legislation
Several countries have implemented legislation mandating the reporting of Scope 3 GHG emissions. These laws vary in scope, applicability, and timelines, reflecting the global push for comprehensive climate-related disclosures.
The countries that have implemented Mandatory Scope 3 reporting include:
- European Union – Under the Corporate Sustainability Reporting Directive (CSRD), large companies and publicly listed firms are required to disclose their full carbon footprint, including Scope 3 emissions. This mandate began in 2024.
- United Kingdom – Climate-related financial disclosures aligned with the Task Force on Climate-Related Financial Disclosures (TCFD) framework are required for large companies in the United Kingdom. Scope 3 reporting is encouraged and mandatory for specific sectors deemed financially material.
- New Zealand mandates Scope 3 emissions reporting for large financial institutions and publicly listed companies under its climate change standards. Reporting began in 2024.
- Switzerland – Large companies must report Scope 3 emissions if they are material to their operations, as part of broader climate-related disclosures under Swiss law.
- Brazil – Publicly held companies, investment funds, and securitisation entities must report Scope 1, 2, and 3 emissions under CVM Resolution 193 starting in 2026.
- Singapore – All public companies and large private entities must report Scope 3 emissions starting in 2026 or later, depending on company size and revenue thresholds.
- Nigeria – Scope 3 emissions reporting is mandatory for public and private companies under the Financial Reporting Council Act beginning in 2028.
- Turkey – Large companies are required to report Scope 3 emissions under the Turkish Sustainability Reporting Standards (TSRS), although the initial reporting phases exclude Scope 3 emissions until after the first two years.
- Australia – Australia has adopted mandatory climate-related financial disclosure legislation aligned with IFRS S2 standards. Starting January 2025, large entities must disclose Scope 3 emissions as part of their broader sustainability reporting requirements.
- California, USA – California’s Climate Corporate Data Accountability Act mandates Scope 3 reporting for companies operating in the state with annual revenues exceeding $1 billion. Reporting will phase in between 2026 and 2030.
In addition, there are several countries encouraging Voluntary or Material-Based Reporting, such as
- Japan – Leading corporations voluntarily report Scope 3 emissions under sustainability initiatives.
- South Korea – Large corporations disclose these emissions voluntarily as part of broader ESG efforts.
- Canada – While currently voluntary, mandatory reporting is expected by 2028.
How does the Scope 3 Emissions Legislation work in Australia?
The Australian Sustainability Reporting Standards (ASRS), implemented under the Corporations Act 2001, require entities to disclose Scope 3 GHG emissions as part of their climate-related financial disclosures.
Some of the key reporting standards and requirements for Scope 3 emissions under ASRS include:
- Mandatory Disclosure Timeline – Scope 3 emissions reporting became compulsory for financial years starting on or after January 1, 2025. Entities are required to disclose Scope 3 emissions from their second reporting year onwards. For example, if the first reporting period starts July 1, 2025, Scope 3 disclosures will be required by June 30, 2027.
- Emission Categories – Entities must disclose Scope 3 emissions across their entire value chain (upstream and downstream) and categorise them according to the Greenhouse Gas Protocol’s 15 categories. These include emissions from purchased goods and services, transportation, waste, business travel, use of sold products, and more.
- Data Collection and Methodology – Entities are encouraged to use primary data (specific to their value chain activities) wherever possible for greater accuracy. Secondary data (e.g., industry averages) may be used initially but should be refined over time. The reporting must align with internationally recognised frameworks like IFRS S2 and the GHG Protocol.
- Relief Periods: – A transitional relief period of three years is provided for Scope 3 disclosures, during which no legal action can be taken against directors for incomplete or inaccurate disclosures related to Scope 3 emissions.
- Integration with Broader Climate Disclosures – Scope 3 emissions are part of broader climate-related disclosures, including climate scenario analysis, transition plans, and climate-related risks and opportunities. These must be included in a Sustainability Report aligned with financial reporting timelines.
Scope 3 Emission Calculations
How do the calculations work in Practise in Australia?
The GHG Protocol enables companies to calculate these totals in line with industry averages. The thinking is that using industry averages provides reasonable estimates when precise data is hard to obtain. But is the method flawed, and does using averages just default to mediocrity? Let’s explore that in more detail.
The Problem with Using Industry Averages
Using an industry average as a measurement metric can present several challenges and limitations. While it provides a general benchmark, its simplicity often obscures critical nuances, leading to misinformed decisions.
Some of the key problems associated with relying on industry averages:
- Lack of Specificity – Industry averages fail to account for the unique circumstances of individual businesses, such as their size, geographic location, customer demographics, or business models. Companies within the same industry often have different strategies, cost structures, or market focuses, making direct comparisons using an average less meaningful.
- Variability and Oversimplification – Industries often include various companies with varying performance levels. Averages smooth out these variations, potentially hiding important outliers or trends. For example, a few high-performing companies in an industry can skew the average upward, giving a distorted view of the “typical/average” performance.
- Limited Context – Industry averages provide numerical benchmarks but lack the context behind those numbers. They do not explain why specific companies perform better or worse than others, or what factors drive success or failure.
- Data Quality Issues – The accuracy of industry averages depends on the quality of the data used. Aggregated data may be outdated, influenced by outliers, or inconsistently reported due to differences in accounting methods or data collection processes.
- Dynamic Nature of Industries – Industries evolve due to technological advancements, regulatory changes, and market trends. Historical averages may not accurately reflect current conditions or future performance expectations.
- Risk of Mediocrity – Using industry averages as a target can lead to complacency. Achieving an “average” performance means outperforming only 50% of competitors but may fall short of leadership standards.
- Potential for Misleading Insights – Averages can create misleading perceptions by masking extremes within data sets. For instance, if one company significantly outperforms while others lag far behind, the average fails to represent either group’s reality. This is sometimes referred to as the “average trap,” where decision-makers are misled into thinking their performance aligns with broader trends when, in fact, it may not.
- Misaligned Strategic Goals – Relying solely on averages may lead businesses to prioritise metrics that do not align with their strategic objectives, creating perverse incentives or suboptimal outcomes.
Is there a better method of calculating Scope 3 Emissions?
At SCIAR, we firmly believe the current methods for calculating Scope 3 emissions are severely flawed for Bulk Commodity Producers. These methods are too open to miscalculation, as any system that relies on guesswork & manual data entry methods. While we understand why these methods are being used, we firmly believe there is a better way.
That is why the team at SCIAR in conjunction with a consortium of the worlds leading companies in the Commodity, Shipping & Carbon Measurement sectors are bringing together all the pieces of the puzzle that will for the first time in the world allow Bulk Commodity producers to accurately show their EXACT Scope 3 emissions for production, transportation, storing, shipping and consumption of their Bulk Commodity.
Accurately measuring and reporting Scope 3 emissions across the entire production-to-consumption lifecycle of a bulk commodity (e.g., metals, coal, or minerals) offers significant strategic, operational, and reputational benefits.
Here are the key advantages:
Enhanced Risk Management
- Identify Emission Hotspots: Pinpoint high-emission stages (e.g., transportation, processing, or customer use) to prioritise reduction efforts.
- Mitigate Regulatory and Financial Risks: Proactively address tightening global regulations (e.g., EU CSRD, Australia’s ASRS) and avoid penalties or supply chain disruptions.
Improved Stakeholder Trust and Market Positioning
- Investor Appeal: Transparent reporting attracts ESG-focused investors, as 44% of companies now set decarbonisation targets.
- Customer Demand: Meet growing expectations from downstream partners (e.g., steelmakers) needing low-carbon inputs to meet their Scope 3 goals.
- Competitive Differentiation: Companies like BHP and Tata Steel use granular emissions data to lead sustainability rankings and secure contracts in green supply chains.
Cost Savings and Efficiency Gains
- Resource Optimisation: Digital tools (e.g., process digital twins) reduce waste by reconciling production data with emissions, cutting costs in energy, water, and materials.
- Supply Chain Collaboration: Shared emissions data fosters innovation with suppliers, such as switching to low-carbon transport or sustainable extraction methods.
Strategic Decarbonisation Opportunities
- Targeted Reductions: Scope 3 often constitutes >90% of total emissions for bulk commodities. Accurate data enables science-based targets (SBTi) and aligns with global net-zero goals.
- Circular Economy Integration: Track product reuse/recycling emissions to design longer-lifecycle commodities.
Regulatory and Compliance Readiness
- Audit-Proof Reporting: Centralised, validated data systems streamline compliance with standards like ASRS, IFRS S2, or GHG Protocol.
- Avoid Double-Counting: Resolve overlaps (e.g., metallurgical coal used in steelmaking) to ensure accurate disclosures.
Innovation and New Business Models
- Low-Carbon Product Premiums: Charge premiums for commodities with verified lower embedded emissions (e.g., green aluminium).
- Partnerships: Collaborate with suppliers on carbon capture, renewable energy, or alternative materials to unlock new revenue streams.
Conclusion
Addressing Scope 3 emissions is no longer optional—it’s essential for businesses committed to long-term success in a rapidly evolving world.
For bulk commodity firms, robust Scope 3 reporting transforms sustainability from a compliance burden into a strategic lever. It drives operational efficiency, strengthens stakeholder relationships, and positions companies to lead in decarbonised markets while mitigating transition risk.
At SCIAR, we are critical of current Scope 3 emissions calculation methods, which we believe are flawed due to reliance on averages, guesswork, and manual data entry. To address this, we are collaborating with leading companies in the commodity, shipping, and carbon measurement sectors to develop a groundbreaking new system.
This system aims to accurately measure Scope 3 emissions across the entire lifecycle of bulk commodities, including production, transportation, storage, shipping, and consumption. Such precise tracking would provide strategic, operational, and reputational advantages for bulk commodity companies.
If you would like to learn more about this new, groundbreaking system, please stay tuned to our website for updates in the coming weeks. Alternatively, feel free to reach out to schedule a confidential call to discuss further.
About the Author
Nick Ogle has over 30 years of experience in enterprise IT, spanning roles in engineering, sales, and marketing across Australia, the USA, and APJ for various IT vendors.
Nick is passionate about entrepreneurship and software innovation, which drive positive change. He is the Sales & Marketing Manager at SCIAR Systems, a Newcastle-based SAAS startup, helping commercialise their groundbreaking Bulk Commodity Logistics and ESG software solutions.
Nick is well-credentialed to discuss issues in Enterprise IT, such as Scope 3 Emissions Reporting, due to his extensive experience in cloud computing architectures, application design, and a broad industry background in IT.
For more information on Nick and to find articles written on the IT sector in the past, please look at his LinkedIn profile or browse some of the additional articles Nick has written for SCIAR Systems.
